Learning Center
Explore helpful articles about buying a home, refinancing, home equity, and second mortgages.
Your Home's Equity Can Help You Get Cash
A cash-out refinance replaces your current mortgage with a larger new loan. For example, refinancing a $200,000 mortgage with a $250,000 new loan creates a $50,000 difference before closing costs, other required payoffs, and adjustments. The net cash you receive may be less.
What can you do with cash-out refinances? Here are some common reasons homeowners choose to refinance and access cash.
Can You Consolidate Debts with Cash-Out Refinances?
A cash-out refinance may be used to pay off higher-interest debts. Compare the new APR, fees, repayment period, and total interest—not just the rate. Extending a short-term debt over many years can increase its total cost, and using your home as collateral introduces foreclosure risk if you cannot repay.
Consolidating debts can also simplify your financial management. Instead of juggling payments on the debts being consolidated, you may repay them through the new mortgage. Other obligations and payments remain.
Can You Pay for Home Improvements with Cash-Out Refinances?
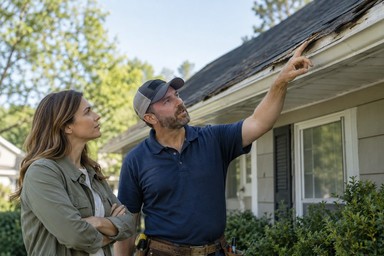
Yes. Financing home improvements and repairs is a popular use of cash from refinancing. You can use the funds for various projects, such as building an addition, finishing an attic or basement, remodeling kitchens and bathrooms, or making significant repairs to roofs, foundations, plumbing, electrical systems, and HVAC systems. The cash can also be allocated for new paint, carpeting, appliances, and other home upgrades.
Remember, you don't have to limit the cash to a single purpose. You could allocate part of the funds toward home improvements and use the rest for debt consolidation.
Can You Pay for College and Investments with Cash-Out Refinances?
Home equity borrowing may be used for education, starting a business, or other eligible goals. Compare student-loan, business-financing, and non-home-secured alternatives. Investment returns and future income are uncertain, while the mortgage still must be repaid; borrowing against your home for these purposes can put the property at risk.
Can You Lower Your Interest Rate with Cash-Out Refinances?
Yes, it's possible to secure a lower mortgage interest rate through a cash-out refinance. Since this process involves obtaining a new mortgage with updated rates and terms, you might qualify for a better rate than your current loan, depending on your existing rate and current market conditions.
A cash-out refinance replaces your existing first mortgage, so its rate and terms change. A separate second mortgage generally leaves the first loan in place and adds another payment. HELOCs and home equity loans are different products. Compare available second-mortgage options if you want to preserve your first mortgage.
✅ A cash-out refinance replaces your first mortgage. If keeping that loan matters to you, this short video introduces a separate second mortgage as an option to compare.
Can You Change to a Fixed-Rate Loan with Cash-Out Refinances?
Yes, refinancing can enable you to switch from an adjustable-rate mortgage to a fixed-rate mortgage. Additionally, you can adjust the length of your mortgage term.
Extending the term may lower your monthly payments, but it could increase the total interest paid over the loan's lifespan. Conversely, shortening the term might raise your monthly payments but could save you money on interest overall.
What Else Do You Need to Know About Cash-Out Refinances?
To qualify for cash-out refinancing, you'll need a significant amount of home equity. This process requires applying for a new mortgage, meeting credit and financial standards, providing necessary documentation, and covering closing costs.
It's important to note that refinancing to access cash may lead to higher minimum monthly payments and increased total interest over the life of the loan, as you will be borrowing more. Carefully weigh the benefits against the costs to make an informed decision that aligns with your financial goals.